Published on : 10/16/2026
Fall Market Outlook 2026
A Quarterly Perspective from Bangor Wealth Management
Financial markets delivered positive results during the third quarter as strong corporate profitability, substantial investment in artificial intelligence, and a resilient economy continued to support investor confidence. While inflation remained above the Federal Reserve's long-term target and bond yields moved higher, equity markets generally advanced as investors focused on earnings growth and the broader economic backdrop.
As we move toward year-end, inflation, interest rates, and corporate profit growth remain among the most important factors influencing the market outlook.
Jump to Section:
THE ECONOMY • GLOBAL EQUITIES • FIXED INCOME MARKETS • LOOKING AHEAD • OUR PERSPECTIVE • MARKET DATA CENTER
The Economy
Solid Growth Continues
Economic growth was solid during the third quarter and is tracking in the mid-3% range, supported by healthy consumer spending and ongoing business investment. The labor market exhibited stability, with average monthly job gains exceeding 50,000 and the unemployment rate unchanged at a historically low 4.2%. Inflation moderated during the period but remained above the Federal Reserve's 2% target.
GDP Growth (Expected)
+3.6%
Inflation
3.4%
Unemployment Rate
4.2%
Average Monthly Job Growth
50,000
Global Equities
Mixed Quarterly Performance
Global equity markets delivered mixed results during the third quarter as robust earnings and investment tied to artificial intelligence were offset by renewed geopolitical tensions, inflation concerns, and monetary policy uncertainty. U.S. equities reached record highs despite headwinds from higher oil prices and rising Treasury yields, with the 10-year Treasury yield approaching a 24-year high.
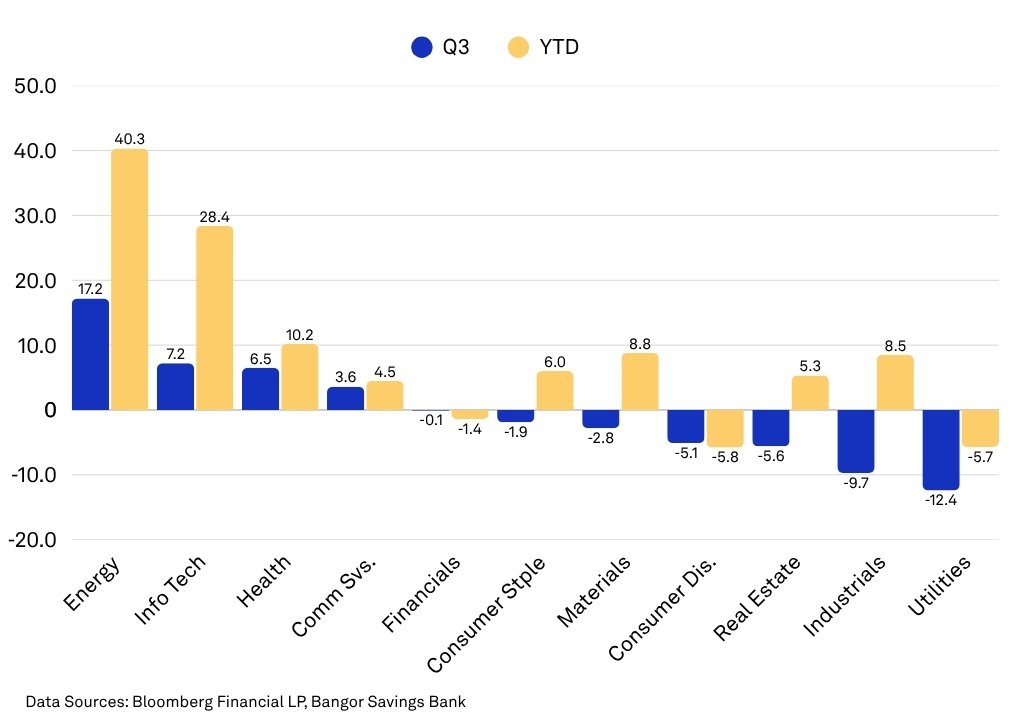
The S&P 500 gained approximately 2.7%, although market leadership remained concentrated in a relatively small group of companies. Corporate profits were strong, with third-quarter earnings growth estimated at nearly 29%, driven primarily by artificial intelligence beneficiaries and energy companies. The Energy and Technology sectors posted gains, while several cyclical and defensive sectors declined, underscoring the benefits of diversification.
Performance Drivers
Energy
+17.2%
Energy led sector performance as firmer oil prices and renewed supply concerns supported earnings expectations.
Technology
+7.2%
Technology stocks advanced as ongoing investment in AI infrastructure and computing capacity supported expected profit growth.
Utilities
-12.4%
Utilities were the weakest-performing sector as higher interest-rate expectations weighed on rate-sensitive industries.
Featured Performance Statistic
U.S. Treasury 10-Year Note Yields
U.S. Treasury 10-Year yields rose by 82 basis points as the Federal Reserve increased its target interest rate by 25 basis points to 4.0% in response to persistent inflationary pressures. This marked the first increase in the federal funds rate since June 2023 and the largest quarterly rise in 10-Year Treasury yields since June 2022.
Fixed Income Markets
Global fixed income markets came under pressure as bond yields rose to multi-decade highs amid renewed inflation concerns, expanding fiscal deficits, and solid economic activity.
Expectations for higher interest rates were reinforced by persistent price pressures, strong capital demand, and increased bond issuance to finance growing government borrowing needs. While higher yields weighed on bond returns during the quarter, they also improved the outlook for fixed-income investors by enhancing income opportunities and prospective long-term returns.
Looking Ahead
Themes to Watch
Market Resilience
Markets were supported during the third quarter by strong corporate profitability, substantial investment in artificial intelligence, and a favorable economic backdrop despite above-trend inflation and elevated bond yields.
Inflation & The Federal Reserve
Investors will remain focused on the path of inflation, the duration of the Federal Reserve's tightening cycle, and the sustainability of profit growth amid historically elevated margins.
Midterm Elections
The upcoming midterm elections may also contribute to market volatility as investors assess potential changes in fiscal, regulatory, and economic policy.
Our Perspective
While near-term uncertainty is likely to persist, we believe long-term investment success is driven by disciplined portfolio management, diversification, and a steadfast focus on financial objectives rather than short-term market fluctuations. Our approach remains centered on balancing opportunity and risk in a manner consistent with each client's goals and risk tolerance.
As always, we welcome the opportunity to discuss your portfolio and investment strategy.
Market Data Center
MAJOR ASSET CLASS RETURNS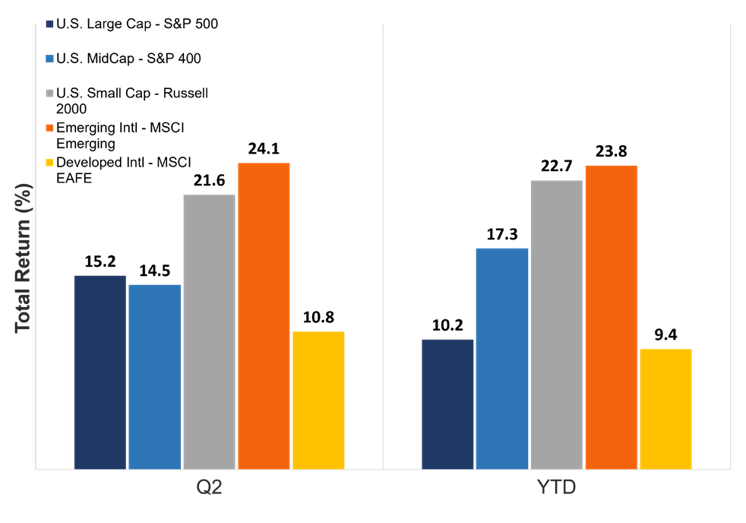
S&P 500 SECTOR RETURNS
SIZE & STYLE RETURNS
| Quarter-to-date | Year-to-Date | |||||
|---|---|---|---|---|---|---|
| Value | Core | Growth | Value | Core | Growth | |
| 2.6% | 1.8% | 0.9% | Large | 19.2% | 12.3% | 6.3% |
| -2.0% | -3.0% | -5.8% | Medium | 15.3% | 11.8% | 1.0% |
| -4.8% | -7.2% | -9.4% | Small | 17.2% | 13.9% | 10.8% |
EQUITY INDEX RETURNS
| Index | YTD | 1 YR | 3 YR |
| U.S. Large Cap - S&P 500 | 12.7% | 15.7% | 22.8% |
| Dow Jones Industrial Average | 7.2% | 11.5% | 17.0% |
| NASDAQ Composite | 16.1% | 19.3% | 27.5% |
| U.S Mid Cap - S&P 400 | 9.9% | 11.7% | 14.5% |
| U.S. Small Cap - Russell 2000 | 13.9% | 16.4% | 17.7% |
| Developed International - MSCI | 10.9% | 16.4% | 19.1% |
| Emerging International - MSCI Emerging | 23.5% | 29.4% | 24.5% |
| MSCI All Country World Index | 13.4% | 17.2% | 22.2% |
U.S. FIXED INCOME RETURNS
| Index | YTD | 1 YR | 3 YR |
| Bloomberg U.S Aggregate | -2.9% | -1.8% | 4.34% |
| Bloomberg Gov't/Credit | -2.8% | -2.0% | 4.08% |
| Bloomberg U.S. TIPS | -2.1% | -2.0% | 3.89% |
| Bloomberg U.S. Credit | -3.0% | -2.2% | 5.16% |
| Bloomberg Corporate High Yield | 0.1% | 1.4% | 8.33% |
OTHER
| | 9/30/2026 | 12/31/2025 | 12/31/2024 |
| Fed Funds Target | 4.0% | 3.8% | 4.5% |
| 30-Year Fixed Mortgage | 7.2% | 6.3% | 7.3% |
| WTI Oil ($/barrel) | $90 | $57 | $72 |
| U.S. Dollar ($) | $101 | $98 | $108 |
| Gold ($/oz) | $4,157 | $4,319 | $2,625 |
| Bitcoin | $83,621 | $87,648 | $93,714 |
U.S. TREASURY MARKET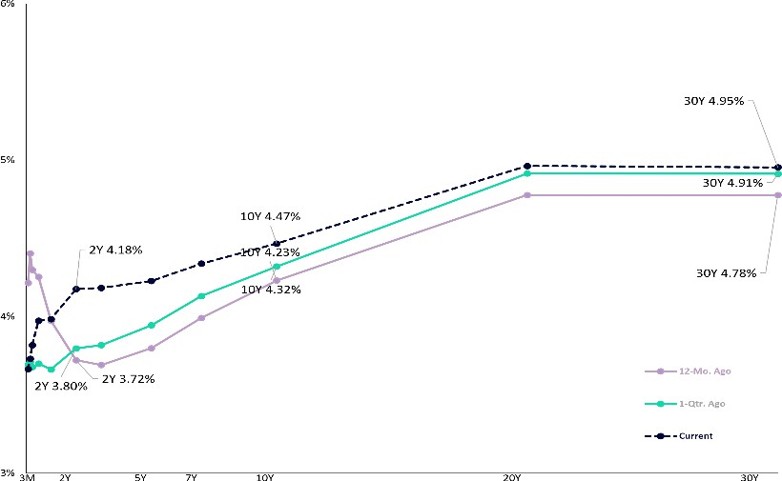
| Maturity | Current | 1-Qtr. Ago | 12-Mo. Ago | 1-Mo. Change |
| 3-Month | 4.1% | 3.8% | 3.9% | 0.3% |
| 6-Month | 4.3% | 4.0% | 3.8% | 0.4% |
| 1-Year | 4.5% | 4.0% | 3.6% | 0.6% |
| 2-Year | 4.9% | 4.2% | 3.6% | 0.7% |
| 5-Year | 5.1% | 4.2% | 3.7% | 0.9% |
| 10-Year | 5.3% | 4.5% | 4.2% | 0.8% |
| 30-Year | 5.6% | 5.0% | 4.7% | 0.7% |
Source: Bangor Wealth Management and Bloomberg. Data as of 9/30/2026. Past performance is no guarantee of future results.
Connect With Bangor Wealth Management
Questions about your portfolio, retirement strategy, or investment allocation?
Contact your Bangor Wealth Management team to discuss how current market conditions may affect your long-term financial goals.
Source: Bangor Wealth Management and Bloomberg. Data as of June 30, 2026. Past performance is no guarantee of future results. Wealth Management products are not FDIC insured, are not bank guaranteed, and may lose value.
NOT FDIC INSURED | NO BANK GUARANTEE | MAY LOSE VALUE
Bangor Wealth Management of New Hampshire LLC is a wholly-owned subsidiary of Bangor Savings Bank.